Wind Mitigation Insurance Discount in Cape Coral
How the Wind Mitigation Discount Is Applied
The wind mitigation insurance discount in Cape Coral comes off the windstorm portion of your premium . Here’s how it works and how the credits get applied. Most people book a wind mitigation inspection for one reason — to knock down an insurance premium that’s climbed way too high. Fair enough. So let’s walk through how that money actually shows up, because it’s not magic. It’s worth understanding before you spend a dime.
The credits go against the windstorm part of your premium.
A chunk of your Florida homeowners premium is specifically the wind/hurricane risk. That’s the part a wind mitigation report affects. When the inspection documents features like a strong roof-to-wall connection, a code-compliant roof covering, secondary water resistance, or protected openings, your insurer applies discount credits to that windstorm portion.
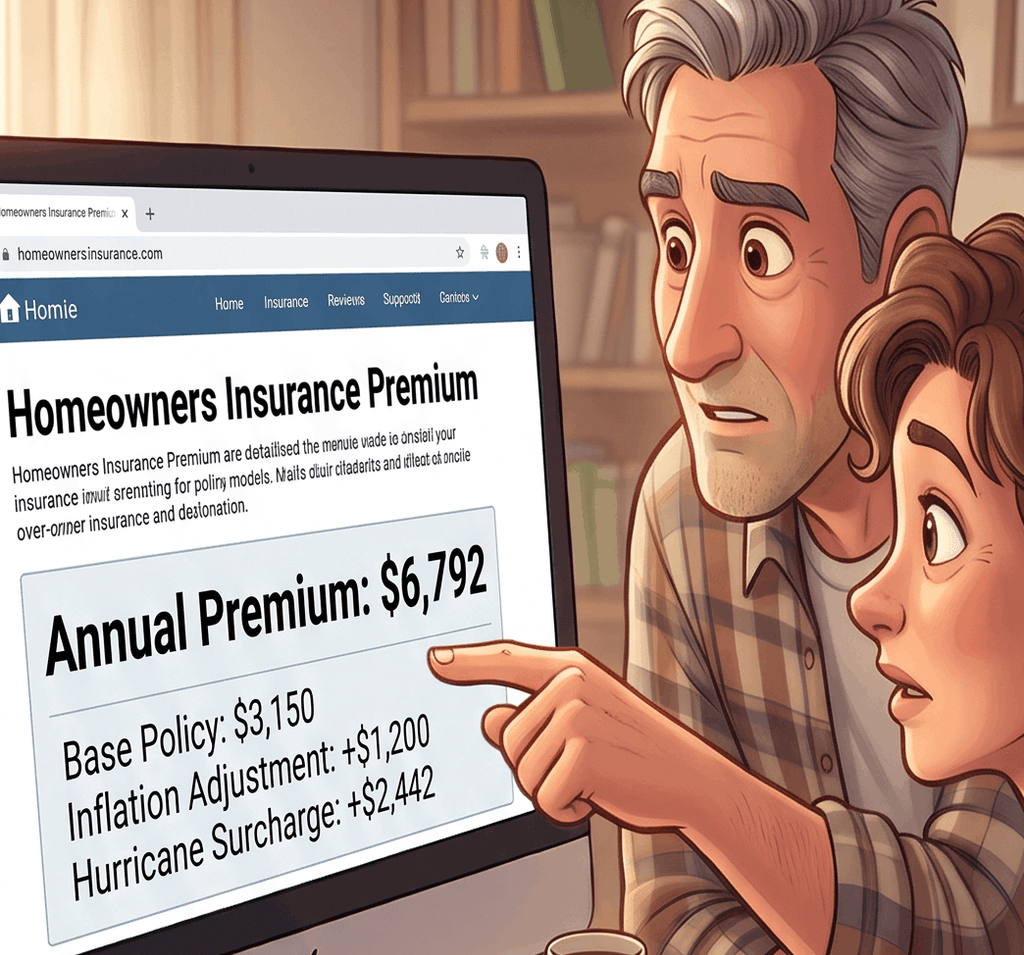
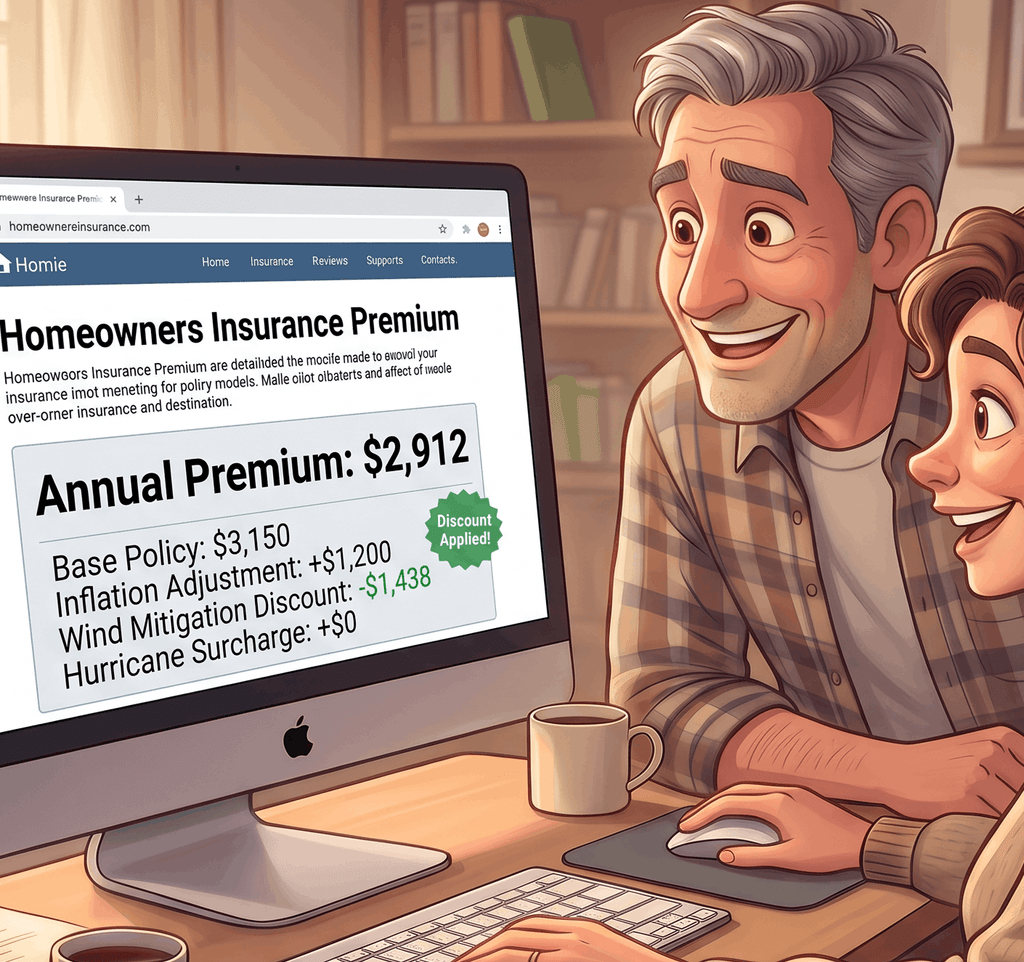
How much? It genuinely depends on the home. Credits commonly land somewhere in the range of a modest discount up to a large one. In real dollars that can mean anywhere from a few hundred dollars a year to well over a thousand for a home that checks a lot of boxes. Anyone quoting you a precise, guaranteed number before they’ve seen your house is guessing. What I can tell you is that the homes with newer roofs, good hurricane strapping, and impact protection tend to save the most.
What happens with the report.
After I inspect, you get the finished report the next business day as a PDF. You hand it to your insurance agent, they apply whatever credits your home earned, and it stays on file. The form is generally good for up to five years, provided you don’t make major changes to the roof, windows, or doors. So one inspection usually keeps working for you across several renewals.
The number people forget.
Here’s the part I always come back to: the reason those features save you money is that they’re the same features keeping your roof attached and the water out during a hurricane. The discount is real and it’s nice. But in Southwest Florida, documenting how your home holds up in a storm is about protecting your property and the people living under that roof… The savings are the bonus on top.
If you want the fuller list of what a wind mitigation inspection does for you beyond the premium, it’s laid out here. And if you’re tempted by a suspiciously cheap quote, read this first. A report that misses credits or gets bounced by your carrier costs more than it saved.
When you’re ready, get a free online estimate. It takes about ten minutes for us to reply via email and there’s no obligation, no mailing list.
How does a wind mitigation inspection lower my insurance? The inspection documents storm-resistant features — roof shape, roof-to-wall connection, roof covering, secondary water resistance, and opening protection — and your insurer applies discount credits to the windstorm portion of your premium for each feature your home qualifies for.
How much can a Cape Coral homeowner save? It depends on the home’s features. Savings commonly range from a few hundred dollars a year to well over a thousand for a home that checks a lot of boxes. Anyone quoting an exact, guaranteed number before seeing your home is guessing.
How long do the savings last? The report is valid for up to five years, as long as you don’t make major changes to the roof, windows, or doors — so one inspection can keep saving you money across several renewals.
Is it worth it if my home is older? Often, yes. Even older homes frequently qualify for credits — a hip roof or a documented roof-to-wall connection, for example. And if you’ve recently added a new roof or impact windows, a fresh inspection can unlock bigger savings right away.
When you’re ready, get a free online estimate. It takes about ten minutes and there’s high pressure call backs, no obligation.